
Can You Have Two VA Loans at the Same Time? What PCS Families Moving to Offutt Should Know
You've got orders to Offutt, and there's a house back at your last duty station you're not ready to sell. Maybe the rent covers the mortgage. Maybe the market's soft and you'd rather wait. Either way, one question keeps coming up: can you use your VA loan again while the first one is still open?
A lot of military families assume the answer is no. They sell a house they'd rather keep, or they give up the VA loan and put money down on a conventional one.
The real answer is often yes. It comes down to how much of your VA entitlement is still tied up in your first loan, and how much you have left.
Here's how two VA loans at once actually works, and how to run your own numbers.
WHAT IS VA ENTITLEMENT, AND WHY DOES A SECOND VA LOAN GET CONFUSING?
Your VA entitlement is the amount the VA promises to pay your lender if you can't. It's what lets lenders offer zero down. On most loans, the VA guarantees 25% of the loan amount, and that guarantee stays tied to the loan until it's paid off, which usually happens when you sell.
That's where the confusion starts. You've probably heard there's no loan limit on VA loans anymore. That's true, but only if you have full entitlement. The moment part of your entitlement is tied up in a house you still own, county loan limits come back into play. Here's what that means: the VA caps your total guarantee at 25% of your county's loan limit. In 2026, that limit is $832,750 in most counties, including around Omaha, which puts the cap at about $208,000. Whatever is still tied up in your first loan comes out of that.
So the real question isn't whether you can get a second VA loan. It's how much house your leftover entitlement will cover before you'd need a down payment.
SHOULD YOU KEEP YOUR HOUSE AND USE A SECOND VA LOAN WHEN YOU PCS?
It can be one of the best wealth moves a military family makes, as long as you decide with the numbers in front of you, not after you've found the next house.
Keeping the last house means building equity in two places, often with a tenant paying down the first mortgage. But you're also carrying two loans, and your leftover entitlement decides whether the next one is still zero down.
The numbers that decide it: what the rent actually covers after a property manager takes their cut, what repairs look like from a thousand miles away, and how much house your remaining entitlement still buys at your new duty station.
HOW DO YOU USE YOUR VA LOAN TWICE?
Get your Certificate of Eligibility (COE). It shows how much of your entitlement is tied to your current loan. Your lender can pull it for you.
Run your numbers. Start with a quarter of your first loan amount, since that's the part the VA has tied up. Subtract it from $208,000, then multiply what's left by 4. The result is roughly how much house you can buy with no money down.
For example, a $240,000 first loan ties up $60,000. That leaves $148,000 of entitlement. Multiply it by 4, and you can buy about $592,000 of house with zero down.
Make sure you can carry both payments. Your lender will qualify you with both mortgages. Rent from your first house can offset its payment, usually at about 75% of the rent, and a signed lease makes that easier. As with any VA loan, you'll need to move into the new home within 60 days and plan to live there as your primary residence.
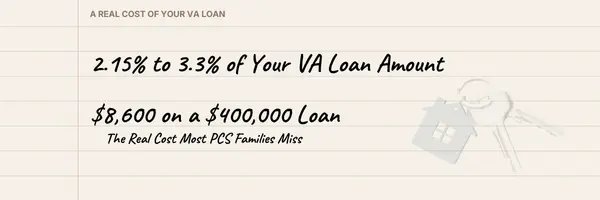
Plan for a higher funding fee. On a second VA loan with no money down, the fee is 3.3% instead of 2.15%. Putting 5% down lowers it to 1.5%, and veterans with a service-connected disability rating are exempt.
Know how to get your entitlement back. Selling the first house and paying off the loan restores it, and there's no limit on that. If you pay the loan off but keep the house, you get a one-time restoration, and refinancing into a conventional loan counts as paying it off. And if another veteran assumes your loan and substitutes their entitlement, yours is freed up.
WHAT DOES A SECOND VA LOAN LOOK LIKE AROUND OFFUTT?
The Omaha area uses the standard $832,750 county limit, so your entitlement math works the same whether you're looking in Bellevue, Papillion, or West Omaha.
Where it gets tricky is coming from a high-cost area. Your first loan was probably bigger, so more entitlement is tied up, but the cap here is the standard $208,000. Say your first loan was $600,000. That ties up $150,000, which leaves about $58,000 of the cap. Multiply it by 4, and you can buy about $232,000 of house with zero down before you'd need a down payment.
Coming from a smaller loan, like the $240,000 example above, you'd have about $592,000 of room. At that point, compare it to what your BAH comfortably covers. For a lot of families, the monthly budget ends up being the real limit, not the entitlement.
And if Omaha is the house you're leaving, it works the other way. The amount tied up in your Omaha loan stays the same wherever you go, but the cap comes from the county where you buy next. If your next duty station is in a higher-cost area, you'll likely have more room.
FREQUENTLY ASKED QUESTIONS
Can you have two VA loans at the same time?
Yes, if you have enough entitlement left. Your remaining entitlement decides how much you can borrow with zero down on the second loan. The new home has to be your primary residence, and anything above your remaining entitlement may need a down payment.
What is VA entitlement?
It's the amount the VA guarantees your lender, usually 25% of the loan. With full entitlement, there's no loan limit. If part of it is tied up in another VA loan, your county's loan limit sets how much you can borrow with zero down.
How do you restore VA entitlement?
Sell the home and pay off the loan, and you can restore it every time. Pay it off but keep the house, including by refinancing into a conventional loan, and you get a one-time restoration. If another veteran assumes your loan and substitutes their entitlement, yours is freed up too.
Can you rent out a house bought with a VA loan?
Yes, once you've lived in it as your primary residence. PCS orders are a common reason to convert it to a rental. The rent can also offset that mortgage when you qualify for your next VA loan.
NEXT STEPS
If you're PCSing to Offutt and weighing whether to keep your current home, start with my Military Buyer Guide.
Then reach out for a PCS planning call. I'll help you run your entitlement numbers against your BAH before you start house hunting.
I am Paul with eXp Realty and I help people buy and sell homes throughout the Omaha metro. I am a 20-year Air Force and Space Force retiree who PCS'd to Offutt AFB and now helps military families navigate the Omaha market. Reach me at paul@gpliving.co or (531) 225-5999.
Categories
- All Blogs (38)
- Buyer Education (1)
- Buyer Resources (1)
- Buyer Tips (1)
- Buyers (4)
- Buying a Home (5)
- Buying and Selling (1)
- First Time Buyers (2)
- Home Equity (1)
- Lifestyle (1)
- Living in Omaha (2)
- Market Reports (5)
- Market Updates (1)
- Military (1)
- Military & Veterans (8)
- Military Buyer (3)
- Military Relocation (2)
- Move-Up Buyers (2)
- Neighborhood Guides (6)
- Offutt AFB (3)
- Omaha Market (2)
- Omaha Real Estate (33)
- PCS (1)
- PCS Move (1)
- PCS Move to Omaha (1)
- PCS to Offutt (5)
- Right Sizing (1)
- Right-Sizing (7)
- Sellers (1)
- Selling a Home (2)
- Selling Your Home (1)
- VA Loan (3)
Recent Posts
GET MORE INFORMATION
